J.P. Morgan Reserve Card Review 2026: Is It Worth It?
Is the J.P. Morgan Reserve Card worth it in 2026? Compare its $795 fee, United Club access, concierge, and why Chase Sapphire Reserve wins for most.
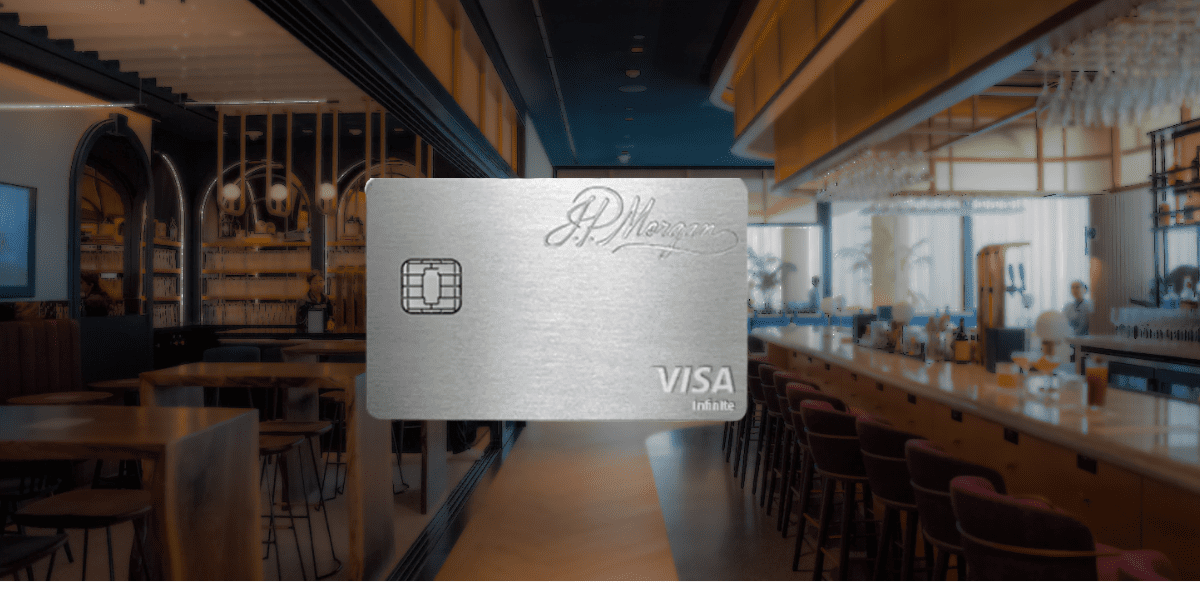
The J.P. Morgan Reserve Card looks more exotic than it is. Under the hood, it is mostly a Chase Sapphire Reserve® with three additions: United Club membership, a stronger concierge, and an unusual credit-reporting advantage.
If you already qualify through J.P. Morgan Private Bank, those extras can make the J.P. Morgan Reserve the better card. If you are thinking about moving assets primarily to get it, I would stop there. The Chase Sapphire Reserve gives most people nearly the same rewards and benefits without requiring a private-bank relationship.
Quick Take
The J.P. Morgan Reserve Card has a $795 annual fee and costs $195 for each authorized user. Its earning rates, annual credits, transfer partners, travel protections, and core lounge access match the Chase Sapphire Reserve.
The extra value comes from:
- United Club membership
- A concierge that can help with difficult dining, travel, and shopping requests
- An account that generally does not appear as a normal revolving tradeline on your personal credit reports while it remains in good standing
For most people, I would get the Chase Sapphire Reserve. It is easier to apply for, has publicly listed terms, and gives you the same core Ultimate Rewards setup. I would choose the J.P. Morgan Reserve only if I already had the banking relationship and expected to use at least one of its three extra features regularly.
J.P. Morgan Reserve vs. Chase Sapphire Reserve
| Feature | J.P. Morgan Reserve Card | Chase Sapphire Reserve® |
|---|---|---|
| How to apply | Through a J.P. Morgan relationship manager | Public application |
| Annual fee | $795 | $795 |
| Authorized-user fee | $195 each | $195 each |
| Earning rates | 8x through Chase Travel℠; 4x on direct flights; 4x on direct hotels; 3x on dining; 1x elsewhere | Same |
| Annual travel credit | $300 per account anniversary year | Same |
| Chase, Priority Pass, and Air Canada lounge access | Included | Included |
| United Club membership | Included for the primary cardmember | Not included |
| Personal credit reporting | Generally hidden as a normal revolving tradeline while in good standing | Normally appears as a revolving account |
| Concierge | J.P. Morgan Reserve concierge | Standard Visa Infinite concierge |
| Intro offer | Usually mirrors the current Chase Sapphire Reserve offer; exact terms come through the relationship manager | Current public offer |
The two cards are close enough that I would not compare every shared credit twice. Start with the Chase Sapphire Reserve benefits you already value, then decide whether United Club access, the concierge, or the credit-reporting treatment changes the answer.
 Chase Sapphire Reserve®
Annual fee: $795
Sebby's Take: This premium travel card is packed with perks like airport lounge access, travel credits, and elevated rewards on travel and dining. It’s a top choice for frequent travelers who want premium benefits and flexible redemption options
Annual fee: $795
Sebby's Take: This premium travel card is packed with perks like airport lounge access, travel credits, and elevated rewards on travel and dining. It’s a top choice for frequent travelers who want premium benefits and flexible redemption options
What Is the J.P. Morgan Reserve Card?
The J.P. Morgan Reserve Card is a private-client Visa Infinite card issued by Chase. It replaced the old J.P. Morgan Palladium Card and is available through qualifying J.P. Morgan relationships rather than a public application page.
The card earns Chase Ultimate Rewards points and shares the Chase Sapphire Reserve’s transfer partners. It also carries the same broad collection of travel credits, hotel credits, dining credits, airport lounge access, and travel protections.
The card uses the same Ultimate Rewards ecosystem and everyday earning rates as the Chase Sapphire Reserve, then adds several services for private-bank clients.
How Do You Get the J.P. Morgan Reserve Card?
You need a qualifying J.P. Morgan relationship and a relationship manager who can submit the application. J.P. Morgan Private Bank generally targets clients with around $5-10 million in assets, but that is not a published hard cutoff for the card.
There can be flexibility based on the market and the wider relationship. A founder with concentrated private-company equity, a business owner who also banks with J.P. Morgan, or someone with significant investable assets may not fit a single numerical test. Investments held with J.P. Morgan can matter; the money does not have to sit idle in cash.
The application process is also different from a normal Chase card. Your relationship manager sends the application, you sign it, and the bank reviews it. The intro offer usually mirrors the current Chase Sapphire Reserve offer, although the exact terms come from your relationship manager. Access to private banking does not guarantee credit approval or a specific credit line.
I would not move a multimillion-dollar portfolio just to qualify for a credit card. Advisory fees, investment options, lending, business banking, service quality, and taxes have far more financial impact than these card benefits. The J.P. Morgan relationship should stand on its own before the card enters the conversation.
J.P. Morgan Reserve Earning Rates
The card earns:
- 8x Ultimate Rewards points on purchases through Chase Travel, including The Edit℠
- 4x on flights booked directly with airlines
- 4x on hotels booked directly
- 3x on dining worldwide
- 1x on other purchases
The direct airfare and hotel categories are strong because you can book with the provider instead of being forced through a portal. Direct hotel bookings can also preserve hotel points, elite-night credit, and status benefits when the rate is eligible.
General purchases earn only 1x. That creates a tradeoff for someone using the card for a large renovation, art purchase, or expensive trip to take advantage of its credit-reporting treatment. Compare the points with what a 1.5x or 2x card would earn before putting a large uncategorized charge on the J.P. Morgan Reserve.
Credits and Travel Benefits
The J.P. Morgan Reserve shares the current Chase Sapphire Reserve benefit package, including:
- A $300 annual travel credit each account anniversary year
- Up to $500 annually for qualifying prepaid stays with The Edit, split into two credits of up to $250 with a two-night minimum
- Up to $250 in 2026 for qualifying prepaid Chase Travel hotel stays at specified hotel groups, with a two-night minimum
- Up to $300 annually for eligible Sapphire Reserve Exclusive Tables purchases, split between January–June and July–December
- Apple TV and Apple Music benefits through June 22, 2027
- DoorDash, StubHub/viagogo, Lyft, and Peloton benefits with separate activation rules and end dates
- IHG One Rewards Platinum Elite status through December 31, 2027
- A Global Entry, TSA PreCheck, or NEXUS application-fee credit
- Chase Sapphire Lounge access with up to two guests
- Priority Pass access
- Access to select Air Canada Maple Leaf Lounges and Air Canada Cafés when you meet the boarding-pass requirements
Some of these credits are easy to use. The $300 travel credit is still one of the simplest premium-card credits because it applies automatically to a broad range of travel purchases.
Others need a discount. The Edit credit requires prepaid bookings and a two-night stay. The dining credit is limited to participating Sapphire Reserve Exclusive Tables restaurants and is split into two six-month periods. A credit tied to a hotel, restaurant, or service you would not otherwise use is not worth its face value.
My approach is simple: full value for spending already in the budget, partial value when the card changes where or how I buy, and $0 when I would ignore the benefit without the card.
How the United Club Benefit Works
The United Club membership is the biggest difference between the two cards. Starting January 15, 2026, the J.P. Morgan Reserve United Club Access Membership covers:
- The primary cardmember
- One adult guest
- Dependent children under 21
United Premier Gold members and higher receive All Access. That expands guesting to two adults or one adult plus dependent children under 21 and adds access to eligible Star Alliance partner lounges.
The J.P. Morgan Reserve does not have the United Club℠ Card’s $50,000 annual-spend route to All Access. Your route is United Premier Gold status or higher.
You may need to contact the J.P. Morgan Reserve team to activate or correct the membership. Check the United app before traveling rather than discovering an enrollment issue at the lounge.
I am based in San Francisco, which is a United hub, and there are times when United is the most practical airline even if I hold status elsewhere. I can put meaningful value on the membership. If you live near an airport where you rarely fly United, assign it $0. The retail price of a membership does not matter if you would never buy or use it.
The Hidden Tradeline
One of the J.P. Morgan Reserve’s most unusual features is how the account is handled on personal credit reports. While the card remains in good standing, it generally does not appear as a normal revolving tradeline.
Consider a $100,000 credit limit and a $90,000 statement balance after paying for a renovation or an expensive trip. A normal personal card could show 90% utilization for that account. The J.P. Morgan Reserve balance generally stays out of the utilization calculation seen by other issuers.
There are limits:
- J.P. Morgan can see your balance and payment activity.
- Delinquency, default, or nonpayment can still be reported.
- The feature does not make spending more affordable.
- Large purchases outside bonus categories earn only 1x.
- You can often reduce reported utilization on another card by paying before the statement closes.
I view this as a buffer for occasional high spending, not a reason to manufacture large purchases. It is useful when the timing of a legitimate expense would otherwise produce an unusually high reported balance.
Is the Concierge Useful?
The J.P. Morgan Reserve concierge can help with travel, dining, events, shopping, pet care, and unusual requests. You still pay for whatever the concierge books or buys.
The best use is a request where access or expertise is more important than saving a few minutes online. Examples include a restaurant with no public reservation inventory, a complicated paid international itinerary, or an urgent card replacement during a long trip.
The restaurant side depends on relationships and available inventory. A concierge cannot create a table that does not exist, but restaurants sometimes hold space for regulars, hotels, and concierge partners. That can help with difficult reservations in cities such as Paris or Tokyo.
For me, the concierge is the most interesting J.P. Morgan-specific feature. A successful reservation or itinerary can save hours. Someone who prefers booking everything independently may assign it very little value.
Is the J.P. Morgan Reserve Worth $795?
If you already qualify for both cards, the shared $795 annual fee and benefit package simplify the comparison. Focus on what is different:
- United Club membership: How often will you visit, and would you have paid for access another way?
- Concierge: Do you make difficult paid travel or dining requests often enough to use it?
- Credit reporting: Do legitimate large purchases regularly create high statement balances on your personal cards?
- Intro offer: The J.P. Morgan Reserve usually mirrors the current Chase Sapphire Reserve offer, but compare the exact terms before applying.
An existing private-bank client who flies United from San Francisco, Denver, Houston, Newark, Chicago, or Washington Dulles can reasonably prefer the J.P. Morgan Reserve. The same client may prefer the Chase Sapphire Reserve if United Club access is irrelevant, the concierge goes unused, or the exact J.P. Morgan intro offer is weaker than the current public offer.
For everyone else, the Chase Sapphire Reserve is the more straightforward answer. You get the same core points, credits, transfer partners, travel protections, and Chase lounge access without changing your banking relationship.
Who Should Get the J.P. Morgan Reserve?
Consider the J.P. Morgan Reserve if you:
- Already qualify through a J.P. Morgan Private Bank relationship
- Fly United often enough to use United Clubs throughout the year
- Have United Premier Gold or higher and can use All Access guesting and partner lounges
- Make legitimate large purchases and want those balances kept out of normal revolving utilization while the account remains in good standing
- Use concierge help for difficult dining, paid travel, shopping, or special requests
- Already value the shared Sapphire Reserve benefits enough to pay the annual fee
Who Should Get the Chase Sapphire Reserve?
The Chase Sapphire Reserve is better for most readers who:
- Want a normal public application
- Primarily care about Ultimate Rewards points, the $300 travel credit, transfer partners, travel protections, and Chase lounge access
- Rarely fly United or already receive United Club access another way
- Would need to move investments or restructure a banking relationship to qualify for the J.P. Morgan Reserve
- Prefer fully published product terms and an online application
- Would not use the J.P. Morgan concierge or credit-reporting feature
Before applying, run your numbers through the AskSebby Chase Sapphire Reserve calculator. Give each credit the value it has in your life rather than the value shown in marketing materials. If the card fits your spending and travel, you can learn more about the Chase Sapphire Reserve®.
Chase Sapphire Reserve®Annual fee: $795
Sebby's Take: This premium travel card is packed with perks like airport lounge access, travel credits, and elevated rewards on travel and dining. It’s a top choice for frequent travelers who want premium benefits and flexible redemption options
Annual fee: $795
Sebby's Take: This premium travel card is packed with perks like airport lounge access, travel credits, and elevated rewards on travel and dining. It’s a top choice for frequent travelers who want premium benefits and flexible redemption options
Frequently Asked Questions
Is the J.P. Morgan Reserve Card invite-only?
There is no public application. Qualifying J.P. Morgan clients apply through a relationship manager, and the bank still makes a credit decision.
How much money do you need for the J.P. Morgan Reserve Card?
J.P. Morgan Private Bank generally targets relationships around $5 million in assets, but there is no published card minimum that guarantees eligibility. The bank can consider the wider client relationship and local market.
Can you have both the J.P. Morgan Reserve and Chase Sapphire Reserve?
Yes, they are separate card products. Approval and welcome-offer eligibility depend on the terms presented with each application.
Does the J.P. Morgan Reserve appear on your credit report?
While the account remains in good standing, it generally does not appear as a normal personal revolving tradeline. Delinquency or default can still be reported. Treat that as a current practice, not a guaranteed card benefit; it can change.
Does the J.P. Morgan Reserve include United Club access?
Yes. The primary cardmember can bring one adult guest and dependent children under 21. United Premier Gold members and higher receive All Access with broader guesting and eligible Star Alliance partner-lounge access. Confirm that the membership appears correctly in the United app before traveling.
Are J.P. Morgan Reserve points worth more?
No. The card earns Chase Ultimate Rewards points and uses the same transfer partners. Its added value comes from United Club access, concierge service, and the credit-reporting treatment rather than a separate points currency.
Final Thoughts
The J.P. Morgan Reserve is a good upgrade for the right existing private-bank client, but it is not a card worth reorganizing your financial life to obtain. United flyers, heavy concierge users, and people with occasional large card purchases can get genuine use from its extra features.
For most readers, I would choose the Chase Sapphire Reserve. It delivers nearly all of the points, credits, protections, and lounge access that drive the day-to-day value. Run your own numbers, discount the credits you would not naturally use, and let the net value decide.
💳 Featured Card Offers
100,000 bonus points.
In this article
- Quick Take
- J.P. Morgan Reserve vs. Chase Sapphire Reserve
- What Is the J.P. Morgan Reserve Card?
- How Do You Get the J.P. Morgan Reserve Card?
- J.P. Morgan Reserve Earning Rates
- Credits and Travel Benefits
- How the United Club Benefit Works
- The Hidden Tradeline
- Is the Concierge Useful?
- Is the J.P. Morgan Reserve Worth $795?
- Who Should Get the J.P. Morgan Reserve?
- Who Should Get the Chase Sapphire Reserve?
- Frequently Asked Questions
- Final Thoughts
💳 Featured Card Offers
100,000 bonus points.